How Should Your Financial Goals Change Over Time?
Think about what mattered most to you financially ten years ago. Were you focused on paying off student loans, buying your first home, or saving enough to start investing?
Now, you may be thinking about funding your children’s education, making the most of your peak earning years, or determining when you can afford to retire.
And looking ahead, your priorities may shift again toward retirement income, healthcare expenses, supporting family members, or leaving a financial legacy.
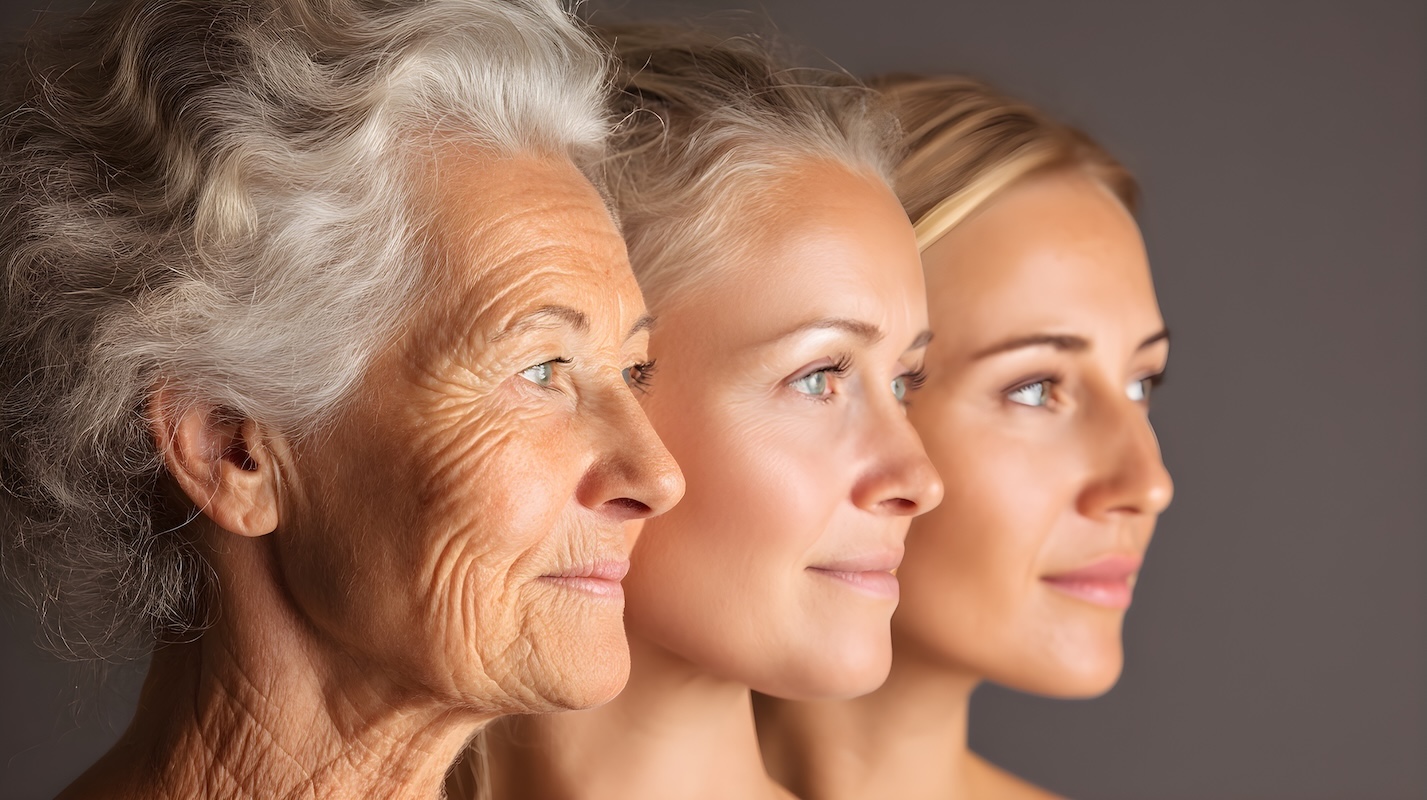
Your financial goals should change as your life changes. The priorities you had in your 20s or 30s may look very different from those you have in your 40s, 50s, or retirement years. As your income, family responsibilities, career, and lifestyle evolve, your financial plan should evolve with them.
The challenge is that your financial goals can change faster than your financial plan.
At iWealth, our Minnesota financial planners believe your financial strategy should reflect where you are today while accounting for where you want to be in the future.
Why Do Financial Goals Change Throughout Your Life?
Consider how your priorities might change:
- In your 20s and 30s: Establishing financial independence, managing debt, building savings, and beginning to invest.
- In your 30s and 40s: Purchasing a home, raising a family, advancing your career, and balancing competing financial commitments.
- In your 40s and 50s: Increasing retirement contributions, managing investments, evaluating taxes, and preparing for major financial transitions.
- In your 50s and 60s: Determining retirement readiness, coordinating income sources, and reviewing healthcare and lifestyle expenses.
- In Retirement: Managing withdrawals, adjusting spending, supporting family members, and considering charitable or legacy goals.
These are general examples, not a timetable you need to follow. The important question isn’t whether you’re meeting financial milestones at a particular age. It’s about whether your financial decisions continue to support what matters most to you.
What Financial Goals Should You Focus on Early in Your Career?
Early in your career, your financial priorities should generally include establishing savings, managing debt, and developing consistent investing habits.
You probably feel like you’re being pulled in several directions. You want to enjoy your income, but you also know you should be saving for the future. Where should you start?
Build a Financial Foundation
Consider focusing on several priorities:
- Emergency Savings: Work toward maintaining three to six months of necessary living expenses, adjusting that amount for your circumstances.
- Debt Management: Develop a repayment strategy for credit cards, student loans, and other obligations, prioritizing higher-interest debt.
- Retirement Contributions: Begin contributing to an employer-sponsored retirement plan, especially if your employer offers a match.
- Consistent Investing: Establish regular contributions based on your income, goals, and risk tolerance.
- Spending Habits: Create a spending plan that balances current needs with future priorities.
You don’t need a substantial income to begin financial planning. In fact, developing good financial habits early may give your investments more time to benefit from compounding. For example, investing $300 per month beginning at age 25 provides considerably more time for potential growth than waiting until age 40.
How Should Your Financial Goals Change as Your Family and Career Grow?
As your career advances and family responsibilities increase, financial planning often becomes more complicated.
- You may be earning more than you did ten years ago, but your financial commitments may also be considerably higher.
- Perhaps you’re paying a mortgage, raising children, helping aging parents, and contributing to retirement accounts.
- At the same time, you want to enjoy the lifestyle you’ve worked hard to build.
The challenge becomes deciding how to allocate your income among competing priorities.
Balancing Today’s Expenses With Tomorrow’s Goals
During these years, your financial plan may need to address:
- Family Expenses: Managing housing, childcare, education, and other household costs.
- College Savings: Evaluating 529 plans and other education funding strategies.
- Retirement Savings: Increasing contributions as your income grows.
- Insurance: Reviewing life, disability, and other coverage as your responsibilities change.
- Tax Planning: Coordinating retirement contributions, investment decisions, and other potential tax strategies.
- Investment Management: Reviewing your portfolio as your assets, time horizon, and financial goals change.
One common concern is whether you’re saving enough for retirement while meeting your family’s current needs. For example, should you increase retirement contributions or put more money toward your child’s college education?
There isn’t one answer for every family.
However, because retirement generally cannot be financed through traditional borrowing as education can, retirement savings often deserve particular attention.
Working with iWealth financial advisors in Minnesota can help you evaluate these competing priorities and understand the trade-offs associated with different decisions.
How Should Financial Goals Change During Your Peak Earning Years?
Your 40s and 50s may represent some of your highest earning years. You may have more opportunities to increase retirement savings, pay down debt, and build investment assets.
But higher income can also create additional financial complexity.
You may have accumulated several retirement accounts, taxable investments, employer stock, real estate, or business interests. Rather than focusing exclusively on accumulating more assets, consider asking:
- Am I saving enough to support my anticipated retirement lifestyle?
- Are my investments appropriate for my retirement timeline?
- Am I taking advantage of available retirement contribution opportunities?
- Could my investment decisions create unnecessary tax consequences?
- Should I prioritize paying down debt before retirement?
- How would an unexpected career change affect my financial plan?
These questions become increasingly important as retirement approaches, as your financial priorities may gradually shift from maximizing accumulation to coordinating investments, taxes, retirement income, and financial flexibility.
This is also a good time to revisit assumptions you made years earlier. The retirement age you selected at 35 may no longer reflect what you want at 55.
Read our new blog: “Why Should Financial Planning Start with Your Life, Not Money?”
How Should Your Financial Goals Change as Retirement Approaches?
As retirement gets closer, your financial priorities begin to shift. After spending decades saving and investing, you now need to think about how those assets will support your lifestyle when you’re no longer receiving a regular paycheck.
You may find yourself asking different questions than you did earlier in your career. As you prepare for retirement, several important decisions deserve your attention:
| Financial Priority | Questions to Consider | What You Should Know |
| Retirement Timing | When can I afford to stop working? | Evaluate your savings, expected expenses, income sources, and retirement timeline. |
| Retirement Income | How will I replace my paycheck? | Determine how social security, pensions, investments, and retirement accounts will fund your expenses. |
| Social Security | When should I begin collecting benefits? | Your claiming age affects your monthly benefit and potential lifetime income. |
| Investment Strategy | Does my portfolio reflect my income needs? | Your investment allocation should account for withdrawals, market volatility, and long-term growth. |
| Taxes | Which accounts should I withdraw from first? | Coordinating taxable, tax-deferred, and Roth withdrawals may help manage your tax liability. |
| Healthcare | How will I pay for healthcare and medicare costs? | Consider insurance premiums, out-of-pocket expenses, and potential long-term care needs. |
| Cash Reserves | How much should I keep available for near-term expenses? | Maintaining accessible savings may help limit the need to sell investments during market declines. |
What Financial Goals Become More Important During Retirement?
Once you’re retired, your priorities may continue to evolve. You may begin thinking about things such as:
- Can I afford to help my children or grandchildren financially?
- Would gifting assets during my lifetime make sense?
- How can charitable giving fit into my financial and tax planning?
- Are my estate documents and beneficiary designations current?
- How might future healthcare or long-term care expenses affect my plans?
- What financial information should my spouse or family members understand?
These decisions often involve more than investments.
For example, helping an adult child purchase a home could affect your retirement liquidity. Making a charitable donation from a retirement account may have different tax implications than donating appreciated investments.
Your Minnesota financial advisor can work alongside your CPA and estate planning attorney to evaluate how these decisions fit together.
How Often Should You Review and Update Your Financial Goals?
You should generally review your financial goals at least annually and whenever a significant life event changes your circumstances.
An annual review provides an opportunity to evaluate your progress, revisit assumptions, and identify areas that may need attention.
You should also consider reviewing your plan following major changes, including:
- Getting married or divorced.
- Having children or grandchildren.
- Receiving a promotion or changing careers.
- Buying or selling a home or business.
- Receiving an inheritance.
- Experiencing a significant change in income.
- Approaching retirement or leaving the workforce.
- Facing unexpected healthcare or family expenses.
Not every life change requires a major adjustment. Sometimes, a small change in savings, spending, or investment allocation may be appropriate. Other circumstances may call for a broader review of your financial strategy.
How Can iWealth Help You Adjust Your Financial Plan?
At iWealth, we believe financial planning should be an ongoing conversation, not a one-time exercise.
As a wealth management firm serving individuals and families in Minnesota and nationwide, we help our clients evaluate how their investments, retirement planning, income needs, and other financial decisions fit together.
The goal is to help you make informed decisions as your financial life evolves.
Explore More
Year-End Financial Strategies
Comprehensive Financial Planning Quick Guide
Smart Money Moves for a Strong Start to the New Year
Comprehensive Financial Planning Quick Guide
Is Your Financial Life More Complicated Than It Should Be?
Comprehensive Financial Planning Quick Guide